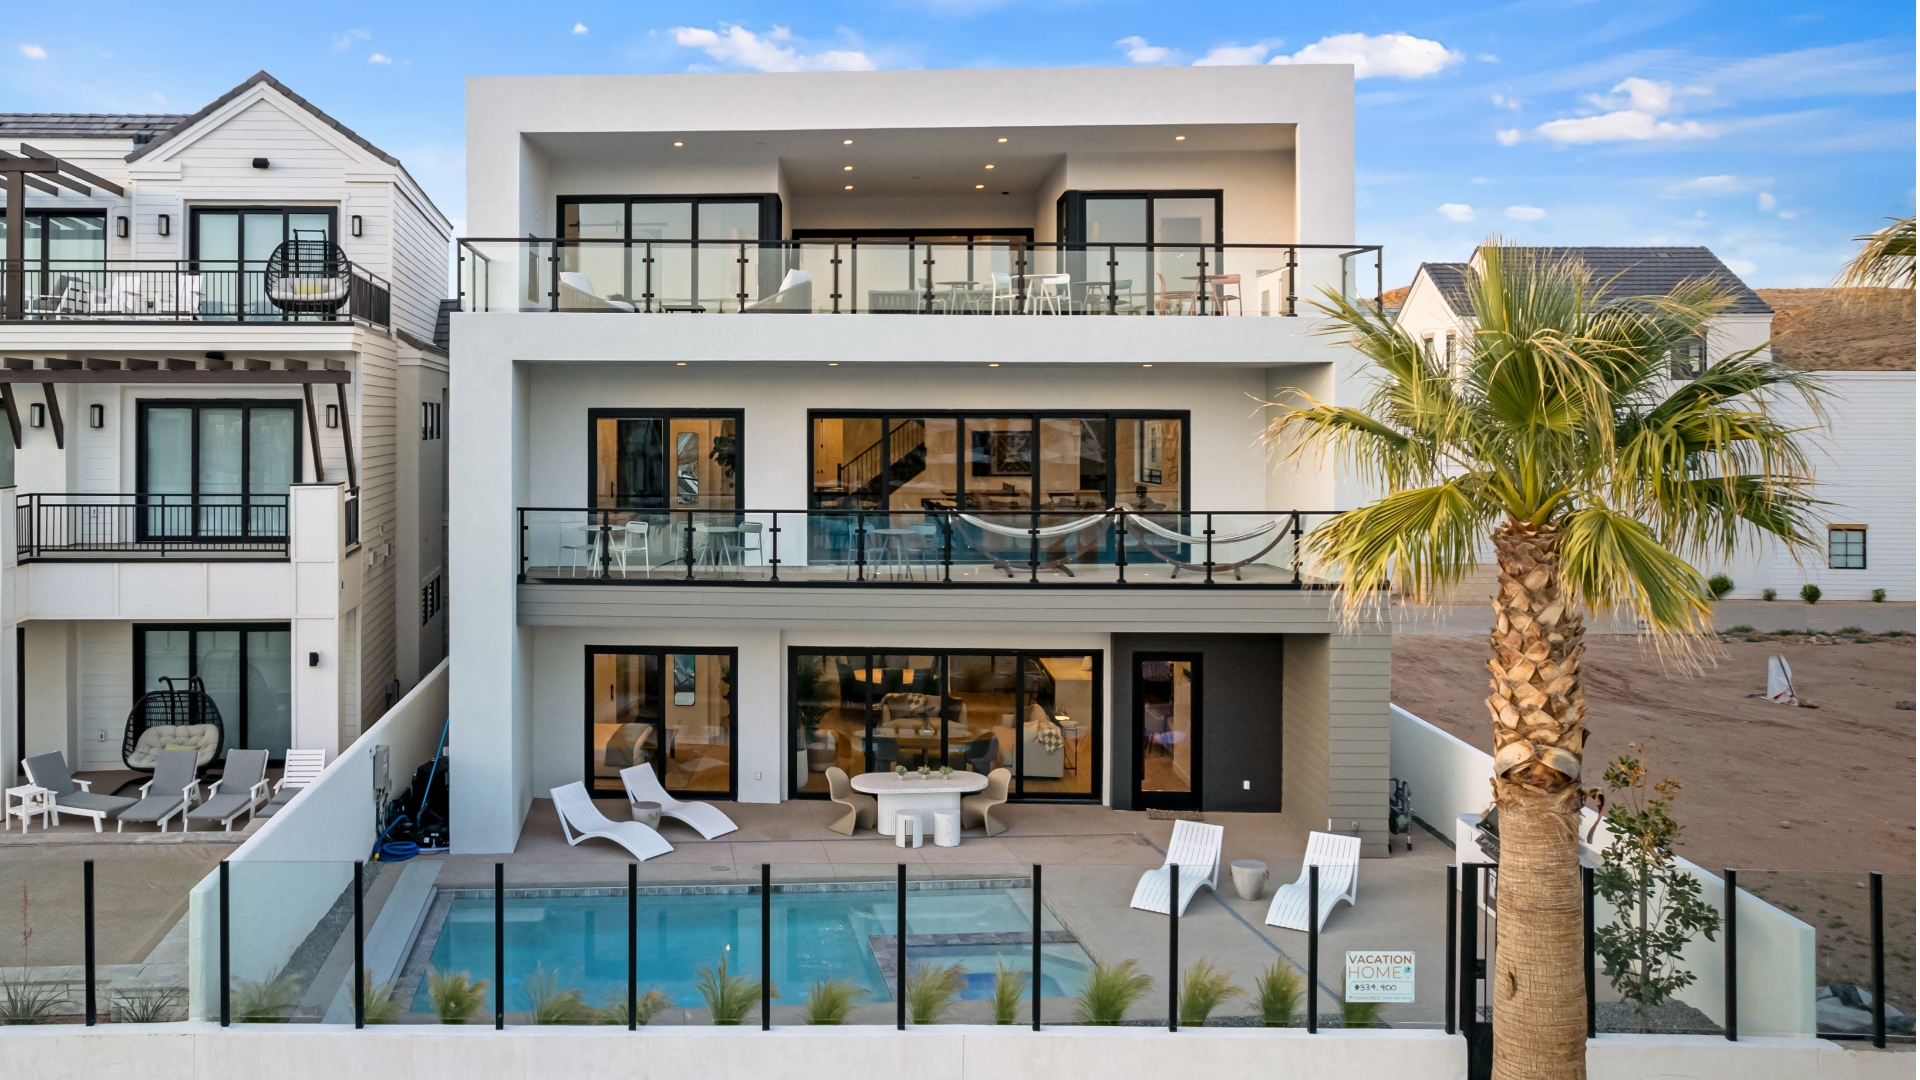
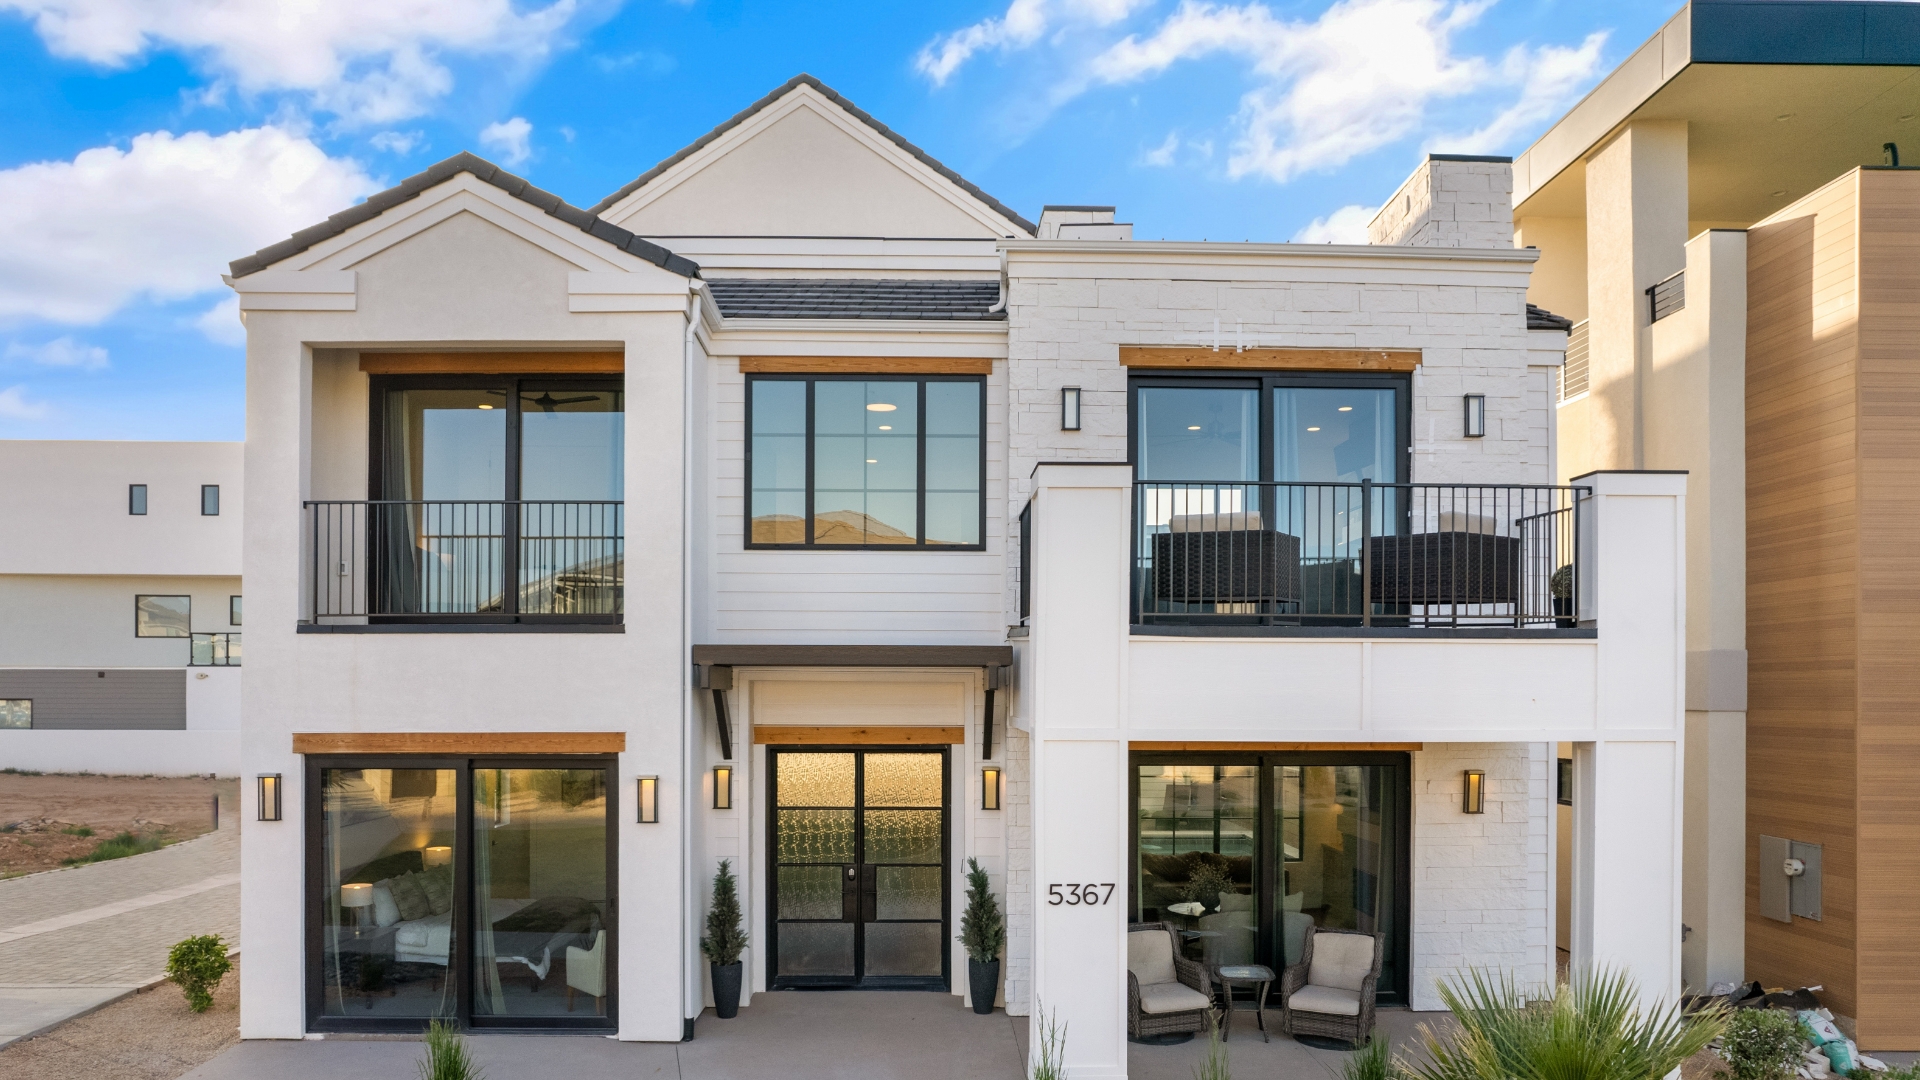
A family can love a vacation home and still ask the wrong question about a 1031 exchange. The useful question is not whether the home is beautiful, or whether the share might appreciate. It is whether this interest is even a candidate to discuss with a tax advisor as replacement property. That screen looks at how the home will be used, whether unused time is actually rented, and what the documents say the buyer receives.
Call (888) 668-6188 to review co-owned vacation homes
1031 exchange eligible fractional vacation homes are not identified by a label on a listing. A share is worth an advisor conversation when the household can show a real rental or investment purpose. The documents also need to tie the interest to real property, rather than only a right to stay, and the family needs a record of how the home will be used. If the plan is mostly family stays and the program does not rent unused time, it is a weak candidate and the family should say so early.
The IRS safe harbor for dwelling units covers rental days and personal use, and only that holding question. It does not bless a brand, a model name, or a brochure. Separate the family's real plan from the ownership papers, then take both to a qualified tax advisor before anyone treats a share as replacement property.
What Should a Family Check in 1031 Exchange Eligible Fractional Vacation Homes? A share is worth a 1031 conversation only when the rights, the rental plan, and the family's own use can be put on paper. A handsome kitchen and a hope of appreciation do not get it there.
"Eligible," in this guide, is a screening word. It means the file looks complete enough to take to a qualified tax advisor. It does not mean the share qualifies, and it does not mean a Fraxioned home, or any other fractional vacation home, will defer tax for this household. Five signals belong in that file before the call.
The home is a real dwelling. Revenue Procedure 2008-16 describes a dwelling unit as real property improved with a house, apartment, condominium, or similar improvement that has sleeping space, a bathroom, and cooking facilities. A furnished vacation home usually fits that description. A points program or a club that only books someone else's inventory does not, and it should come off the list before the tax conversation starts.The documents tie the interest to real property. Read whether the buyer receives deeded real property, an interest in the entity that holds the deed, or a contractual right to book nights. Points, club access, and a membership card are not the same fact. The label "fractional" does not decide which one this is.Unused time is actually rented to paying guests. A salesperson's "you could rent it" is not a rental program. The file should show who lists the nights, who sets the rate, and who is allowed to stay without paying.The family's plan leaves room for that rental. Write down the holidays and school breaks this household expects to keep. A plan that fills the calendar with family stays leaves a different set of facts than a plan that keeps a real block of nights for paying guests.The packet exists before the meeting. Ask for the operating agreement, the rental-program description, and the title documents first. An advisor cannot review a brochure as if it were the contract.Hoping the home will rise in value is not a substitute for investment use. In Moore v. Commissioner , T.C. Memo. 2007-134, the owners exchanged one never-rented lakeside vacation home for another and used both only personally. The Tax Court held that the mere hope of a later gain does not create investment intent when the property is used as a residence. That is the cleanest reason to separate a family's love of a place from the facts an advisor has to test.
The papers also have layers. A property-specific company can hold the deed while the buyer holds a membership interest, and a use schedule can limit what either of those words means in practice. If the packet is still a pile of links, the fractional ownership due diligence checklist is a practical way to sort title, governing documents, rental operations, and use limits before the advisor call. None of those checks is a determination that a particular share qualifies.
Does the Home Rent, or Is It Reserved for the Family? The practical screen is simple. Will unused nights go to paying guests, or is the home reserved for owners and the people they invite? That single fact changes whether a fractional vacation home belongs in a 1031 conversation at all.
Fraxioned uses two ownership models, and they are not interchangeable on this point. Collective lets owners use the time they want and has the company rent unused nights, with the rental work handled by the manager. Exclusive does not permit nightly rentals. It is for owners and their guests. A household that wants a private house, with no strangers in the kitchen, is describing Exclusive. A household that is willing to leave a real share of the calendar for paying guests is describing Collective. The model name is a clue. The written rental policy is the fact.
Property used solely as a personal residence sits outside section 1031. Revenue Procedure 2008-16 restates that background. Revenue Ruling 59-229 concluded that an exchange of personal residences may not be deferred under section 1031, because a residence is not held for business or investment. Section 2.05 of Revenue Procedure 2005-14 says the same thing in shorter form: section 1031 does not apply to property used solely as a personal residence. A court made the same point in Starker v. United States : use of property solely as a personal residence is antithetical to holding it for investment.
Picture a family buying a share so grandparents, parents, and cousins can gather at the same lake house, and so nobody else ever stays there. That is a coherent reason to buy. It is a weak set of facts to bring to an advisor as replacement property. The furnishings, the view, and the LLC do not change the use. The advisor will look at how the home is held, whether it is offered to paying guests, and how the owners actually use it.
A program that really rents unused nights gives the advisor different facts. It still does not make the home, the model, or the share qualify. Company materials describe Collective homes as 1031 eligible because unused time can be rented. Treat that sentence as a description of the program, not as a conclusion for any household. Personal use and fair rental are questions for the family's own tax advisor, who has to read the exchange, the ownership documents, and the rental terms together. The page on how co-ownership works is the right background for that meeting, not a substitute for it.
Households comparing a rental-enabled share with a private one should read the guide to choosing Collective or Exclusive and then match the choice to the calendar they will actually keep. Fair rental and the personal-use limits are fact questions. They are not a slogan on a listing.
Someone who already owns a whole second home, and is asking whether that house can be relinquished, is in a different article. Start with the second home 1031 exchange guide, then come back here only if the replacement idea is a fractional share.
How Should a Household Read Its Own Calendar First? The calendar is the document most families skip, and it is the one an advisor will ask for. A fractional vacation home can look flexible in a sales meeting and still be planned, in the buyer's head, as a holiday house. Write the real plan down before anyone uses the phrase 1031 exchange eligible fractional vacation homes.
Start with the weeks this household will not give up. School breaks, the week of Christmas, a standing reunion, and the long summer stretch are the usual ones. Put a name next to each block. Then mark the weeks nobody in the household is likely to use, and say whether those weeks would actually be offered to paying guests. A calendar that is full of family names, with a blank "we might rent it" at the bottom, is a personal-use plan. A calendar with named family weeks and a real set of weeks assigned to the rental program is a different plan. Neither one is a tax conclusion. Both are facts.
Two traps show up in that exercise. The first is counting a stay by parents, adult children, or close friends as a rental because someone "could have" paid. Revenue Procedure 2008-16 measures personal use under section 280A(d)(2). Fair rental is judged from the rental agreement itself, including what each side actually agreed to, not from a rate the family mentions later. If the people who stay most often will not be paying a fair rental, write that down. The second trap is assuming every co-owner's calendar is the household's calendar. Other owners' unused nights do not become this household's rental history.
Fraxioned's scheduling is first-come, first-served, with peak access shared across owners rather than awarded by lottery. That is a fairness rule for co-owners. It is not evidence that any owner's unused time is rented, and it is not evidence of investment intent. Exclusive homes are not rented at all. On a Collective home, the rental program is what an advisor needs to see, not the booking rule.
Keep this page to one side. It should be short enough to hand across a table. Include the weeks the household will keep, the weeks it will release, who may stay without paying, and who sets the rate on nights that are released. That page, plus the agreement, is the start of a serious meeting. The vacation home 1031 exchange guide covers the whole-home version of the same use question, for readers who are relinquishing a house they already own rather than screening a share they might buy.
Which Use Tests Does the IRS Safe Harbor Actually Apply? Revenue Procedure 2008-16 is a safe harbor for certain dwelling units. It gives taxpayers a clearer way to show that a property was held for investment or productive business use under Section 1031 when the stated conditions are met. It is not a blanket promise that a fractional vacation home qualifies, and it does not say that a property outside the safe harbor automatically fails. A household considering the whole-home qualification question still needs to review its facts and the other exchange requirements.
The starting point is the property itself. For this procedure, a dwelling unit is real property improved with a house, apartment, condominium, or similar structure that includes sleeping space, a bathroom, and cooking facilities. The relinquished property must have been owned for at least 24 months immediately before the exchange. During each of the two 12-month periods immediately before the exchange, it must have been rented to another person at a fair rental for at least 14 days.
Personal use has its own limit in each of those 12-month periods. It cannot exceed the greater of 14 days or 10 percent of the days the property was rented at a fair rental. The procedure applies the personal-use definition in Section 280A(d)(2), with the related rules identified in the procedure. Fair rental is not just a number chosen after the fact. It is evaluated from all the facts and circumstances when the rental agreement is made, including the parties' rights and obligations.
The same shape of test applies after the exchange to the replacement dwelling. The acquired property is measured over the 24 months immediately after the exchange, with the rental and personal-use standards applied in each of the two following 12-month periods. Meeting this safe harbor addresses only the held-for-investment or business-use question. Other Section 1031 requirements remain open, including whether the ownership and exchange structure satisfy those separate rules.
Questions the safe harbor can help answer
Signal What to ask Dwelling Does the real property have sleeping space, a bathroom, and cooking facilities? Ownership period Was the relinquished dwelling owned for at least 24 months immediately before the exchange, or will the replacement dwelling be held for the corresponding 24 months afterward? Fair rental days Was it rented to another person at a fair rental for at least 14 days in each relevant 12-month period? Personal-use cap Did personal use stay at or below the greater of 14 days or 10 percent of fair-rental days in each relevant period? Other 1031 rules still open Even if these tests fit, what separate Section 1031 requirements apply to the exchange and ownership structure?
These are screening questions, not a determination that any particular share or household qualifies. For the full wording and limits of the safe harbor, read Revenue Procedure 2008-16 and obtain advice based on the specific exchange.
Is the Share Deeded Real Property or Only a Right to Stay? For anyone evaluating 1031 exchange eligible fractional vacation homes, the first document question is not how attractive the property looks. It is what, exactly, the buyer receives. A deeded interest in real property may create a more serious conversation with a tax advisor than a purchase of points, a club membership, or a contractual right to book time. Those arrangements can provide access to a home without giving the buyer an ownership interest in the underlying real estate.
That distinction matters because a 1031 exchange involves property held for investment or productive use and other requirements that must be evaluated together. A label such as “fractional” does not answer the question. Neither does a company’s description of an offering as 1031 eligible. The relevant ownership and use structure has to be established from the actual transaction documents and the buyer’s facts.
Read the deed, entity documents, and use agreement together Fraxioned describes its shared-ownership structure as a deeded share associated with a property-specific LLC. In that structure, the deed is held by the LLC, while the buyer receives a membership interest. The document package also includes an operating agreement and usage-rights paperwork. You can learn more about how those pieces fit together in Fraxioned’s shared ownership structure .
That description is not a conclusion that an LLC membership interest is itself real property, and it does not establish that the interest automatically qualifies for a 1031 exchange. Ask the seller and your advisors to identify the legal nature of each part of the transaction:
Are you receiving an interest in real property? Are you receiving an interest in an entity that owns the real property? Or are you receiving only a license or contractual right to use the home? Also ask how the usage rights, rental activity, transfer provisions, and responsibilities in the operating agreement interact with the ownership documents. A deed, membership certificate, operating agreement, and use agreement should be reviewed as one package, not selected individually to support a preferred answer.
A tax advisor must determine how the arrangement applies to your relinquished and replacement property. If the ownership structure or deed raises a property-law question, a real estate lawyer may also need to review it. For a broader overview of the issues to raise, read 1031 Exchange and Fractional Ownership , while keeping the final analysis specific to your documents and intended use.
Which Documents Should You Gather Before the Advisor Call? A productive call starts with the household's actual plans and the documents that define the proposed ownership. A company page can introduce a property, but it cannot answer every question about your use, title, rental activity, or exchange. Gather the following before speaking with an advisor.
Write down how your household will use the home. Note who expects to stay, whether the home is intended for family gatherings or personal vacations, and how you expect to use peak holidays. Be candid about the pattern you anticipate rather than describing an idealized schedule. Your personal-use plans are part of the facts an advisor needs to review.Ask how unused nights are handled. Find out whether the program permits unused nights to be rented to paying guests, who manages those rentals, and who sets the rate. Do not assume that every fractional ownership model offers the same rental access. Ask for the written policy and any explanation of how owner use and guest stays are treated.Request the operating or co-ownership agreement. This document may explain voting, costs, maintenance responsibilities, scheduling, transfers, and other rights and obligations. Read the agreement with the proposed use in mind, and ask the advisor to identify provisions that could affect your intended ownership or exchange structure.Request a precise description of what you are purchasing. Is the interest a membership interest, a deeded share, a contractual use right, or something else? Also ask who holds the property deed. Fraxioned materials describe ownership tied to a property-specific LLC, with the deed held by the LLC, but the documents for the specific home should control your review. You can browse available homes separately from this document review.Request the rental-program summary, if one exists. It should explain the program's role, guest rules, rate-setting process, and whether any people may stay without paying rent. Those details can matter when an advisor evaluates the difference between personal use, guest use, and rental activity. Keep the summary with the agreement rather than relying on a sales conversation.Book the right professional conversations. Schedule a tax advisor before treating the opportunity as suitable for a 1031 exchange. If an exchange is already underway, include your qualified intermediary as appropriate. For a separate how-to, read this 1031 exchange guide ; for company-level context, see Fraxioned's exchange overview . Neither replaces advice on your facts. Financing is a separate, property-specific question to raise with the relevant professionals.What Does This Screen Leave for Your Tax Advisor? Passing this screen does not make a fractional vacation home 1031 exchange eligible. It only means the household has enough facts to ask a better question, and to hear "not this one" without surprise.
The safe harbor in Revenue Procedure 2008-16 covers one issue: whether a dwelling unit was held for investment or for use in a business. A tax advisor still has to decide the rest for this household and this interest. The screen in this guide leaves several decisions open. It leaves these decisions to the advisor.
Whether this family's actual stays, guest stays, and rental nights meet the safe harbor in each 12-month period, or whether a property outside the harbor could still be held for investment. Whether the specific interest being purchased is like-kind real property, an interest in an entity, or a contractual right to use the home. Identification and closing deadlines, cash or mortgage boot, debt replacement, and state tax. Those belong in the guide to 1031 exchange rules for fractional real estate , and then with the advisor. Whether a reported exchange has to be amended if the replacement home later misses the rental or personal-use pattern the return assumed. Revenue Procedure 2008-16 says a taxpayer in that spot should file an amended return if necessary and stop reporting the deal as a 1031 exchange. Which company to hire. Comparing sponsors is a different job, covered in the guide to fractional real estate companies for a 1031 exchange . A family that wants a private gathering place, with no paying guests, should choose the home for that reason. The motto that fits that choice is "Your Favorite Place With Your Favorite People." It is a reason to buy a share. It is not a reason to call the share a 1031 exchange.
Bring the use notes and the document packet to a qualified tax advisor before anyone treats a listing as replacement property. If an exchange is already open, the qualified intermediary needs the same packet. Company pages, including this one, are not that advice.
Learn how co-ownership actually works
Frequently Asked Questions What does 1031 exchange eligible mean for a fractional vacation home? In this guide it means the share is worth a conversation with a tax advisor, not that the share qualifies. The household should be able to point to a real dwelling, a rental program for unused time, a plan that leaves room for that rental, and documents that show what is actually being purchased.
Is a family-only fractional home a weak 1031 candidate? Yes. If the program does not rent unused nights and the household plans to use the home only as a private gathering place, the facts look like personal use. IRS materials cited in Revenue Procedure 2008-16 treat property used solely as a personal residence as outside section 1031. That is a reason to pause, not a ruling on any one home.
Does a deeded share automatically qualify for a 1031 exchange? No. A deeded interest is a stronger starting point than points, a club membership, or a contractual right to book time. It is not a determination. Fraxioned describes a deed held by a property-specific LLC and a membership interest for the buyer. A tax advisor, and sometimes a real estate lawyer, has to read that package.
What does the IRS safe harbor test, in short? Revenue Procedure 2008-16 says the IRS will not challenge the investment-or-business holding question for a dwelling unit that meets its tests. Those tests look at 24 months of ownership, at least 14 days of fair rental in each of two 12-month periods, and a personal-use cap. The procedure does not say a home outside the harbor fails, and it does not settle any other 1031 requirement.
Which document should we bring to the advisor first? Bring a one-page note of how the household plans to use the home, including peak holidays, plus the operating agreement and a written description of what is being purchased and who holds the deed. Add the rental-program summary if unused nights can be rented. A brochure is not a substitute.
Call (888) 668-6188 to discuss which ownership model fits your household